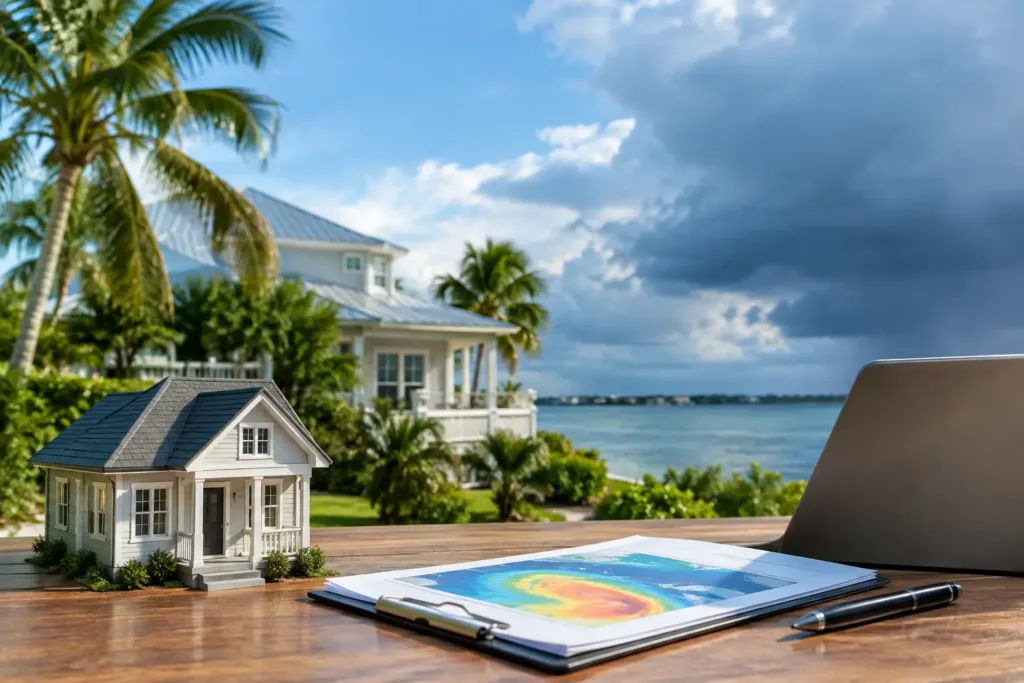
Clearwater, Tampa, St. Petersburg, Cape Coral, and Fort Myers homeowners are seeing a new question enter property decisions: how do flood exposure, wind vulnerability, heat, and rising insurance costs affect a home’s market value? Climate risk appraisals are not a separate substitute for a certified residential appraisal. They are a more informed way of considering risk factors that buyers, lenders, insurers, and the market may already be weighing.
For a homeowner preparing to sell, a buyer comparing two similar homes, or an attorney handling an estate or divorce matter, the distinction matters. An appraisal must remain objective, supported by market evidence, and compliant with USPAP. It cannot speculate about future events. But when climate-related conditions are reflected in a property’s location, condition, insurability, market appeal, or comparable sales, they can become relevant to a credible opinion of value.
What Climate Risk Appraisals Actually Examine
In residential valuation, climate risk is rarely reduced to one score or label. A knowledgeable Real Estate Appraiser considers the property in its actual market context: its elevation, proximity to water, flood-zone designation, roof age and condition, construction quality, storm protections, drainage, history of damage where reliably documented, and the availability and cost of insurance.
The key question is not simply whether a home faces a weather-related risk. Nearly every coastal and inland market has some level of exposure. The question is whether buyers and sellers recognize that exposure and whether it changes what they are willing to pay.
For example, two waterfront-adjacent homes may be physically similar, but one may have a newer roof, impact-rated openings, improved drainage, and a more favorable elevation. If buyers consistently pay more for that combination of features, the market evidence may support a value difference. If insurance quotes or lending requirements materially narrow the buyer pool for another property, that can also influence marketability.
A Home Appraisal does not predict the next hurricane, flood, or insurance renewal. It measures value as of a specific effective date using available, credible market data. That discipline is especially valuable when headlines and uncertainty can otherwise overwhelm a property decision.
Why Insurance Has Become a Valuation Issue
Insurance is often where climate concerns become immediate. Homeowners may reasonably focus on premiums, deductibles, exclusions, and the availability of coverage because those costs affect the practical affordability of owning a property.
An appraiser does not set insurance rates or determine whether a home is insurable. However, a Real Estate Appraisal may need to address market reaction when insurance availability or expense is demonstrably influencing transactions. If buyers are paying less for homes with older roofs, limited wind mitigation, previous water intrusion, or difficult coverage histories, those patterns deserve careful analysis.
This does not mean every higher premium produces a direct dollar-for-dollar reduction in appraised value. Real estate markets are more complicated than that. A desirable location, limited inventory, strong cash-buyer demand, or a recently renovated home can offset some risk concerns. Conversely, a modest issue may have a larger impact in a neighborhood with many competing listings.
The best valuation work identifies what the market is actually doing rather than applying a formula that treats every property alike.
Property Features That Can Matter
Certain features frequently become relevant when analyzing risk and market appeal. These include roof age, roof covering type, hurricane shutters or impact windows, elevation, seawalls, drainage systems, updated electrical components, and documented repairs after water or wind damage.
Their value contribution depends on the market and the evidence. Impact windows, for instance, may improve safety, comfort, and insurability, but the appraiser still needs support from comparable sales, paired-sales analysis, recognized cost data, or other accepted valuation methods before making an adjustment.
Homeowners should also understand that improvements do not always return their full cost in market value. A new roof may be essential to preserving marketability and satisfying an insurer or lender, yet its contributory value will vary based on the home’s age, price range, and competitive set.
How a Credible Appraisal Handles Flood and Wind Exposure
Flood and wind exposure require more than a quick map check. Location is a fundamental part of real estate value, but two properties within the same broad zone can have significantly different characteristics. Elevation, drainage, building design, proximity to open water, and neighborhood access can affect buyer perception and practical risk.
A certified Home Appraiser reviews relevant property characteristics and selects comparable sales that reflect similar market influences whenever possible. In Cape Coral and Fort Myers, for example, waterfront location can carry substantial value, while canal access, seawall condition, storm exposure, and property elevation may require closer analysis. In Clearwater, Tampa, and St. Petersburg, neighborhood-specific demand, older housing stock, and proximity to the bay or Gulf can also shape the appropriate comparable set.
Comparable sales are not chosen merely because they are close by. A credible analysis considers similarity in location, physical characteristics, condition, appeal, and sale date. When a subject property has a known condition issue or a material feature related to wind or water resilience, the appraiser must determine whether the selected sales provide meaningful evidence for a supported adjustment or explanation.
That is why automated estimates can be limited in these situations. An algorithm may recognize square footage and recent sale prices, but it may not understand the market significance of a recently replaced roof, a compromised seawall, post-storm repairs, or a location difference that local buyers view as meaningful.
When You May Need a Climate-Informed Home Appraisal
A climate-informed appraisal can be particularly useful when the property decision involves uncertainty, competing opinions, or a need for an independent report. Homeowners often request one before listing a home with recent storm-related repairs, after making major resilience improvements, or when deciding whether to invest in costly updates.
Buyers may benefit from an independent valuation when a property’s insurance costs, roof condition, flood exposure, or prior repairs raise questions about whether the contract price reflects the full picture. Lenders need an appraisal that meets lending requirements, while attorneys and estate representatives need reports that are clear, well-supported, and defensible.
The intended use matters. A mortgage appraisal has lender-specific requirements and an established scope of work. An appraisal for probate, divorce, litigation, or pre-listing planning may require a different effective date, research process, or reporting format. Communicating the purpose early helps the appraiser develop an assignment that fits the decision at hand.
What Homeowners Should Provide to the Appraiser
The appraiser develops an independent opinion and cannot advocate for a predetermined result. Still, homeowners can provide factual documents that improve the accuracy of the analysis. Useful information may include permits and invoices for roof replacement, window upgrades, drainage work, seawall repairs, mitigation improvements, or remediation following a documented loss.
It is also helpful to identify renovations that may not be obvious during an inspection, such as upgraded insulation, electrical work, plumbing replacement, or improvements behind walls. If a property has had damage, be straightforward about what occurred, when it occurred, and what repairs were completed. Clear documentation is far more useful than unsupported assurances.
Avoid assuming that an insurer’s replacement-cost figure, a tax assessment, or an online estimate establishes market value. Each serves a different purpose. Market value is shaped by informed buyers and sellers, competitive alternatives, financing conditions, and the property’s specific characteristics as of the appraisal date.
Choosing a Local Appraiser for a Risk-Sensitive Assignment
Climate-related valuation questions make local competency especially important. A Real Estate Appraiser Clearwater homeowners hire should understand the distinctions among nearby neighborhoods, housing types, waterfront influences, and buyer expectations. The same is true for a Real Estate Appraiser Tampa, St. Petersburg, Cape Coral, or Fort Myers clients rely on for a significant financial or legal decision.
Look for state certification, experience with the relevant property type, USPAP-compliant reporting, and a willingness to explain the scope of work. A qualified appraiser should be able to describe what the report can address, what falls outside the appraisal assignment, and what documents may be useful.
My Florida Home Appraisal brings more than 25 years of residential valuation experience to assignments where accuracy, local market knowledge, and report clarity matter. Whether the need is lending, estate planning, litigation support, or a private decision, the goal remains the same: an unbiased value opinion grounded in credible evidence.
A changing risk environment does not make objective valuation less possible. It makes careful, property-specific analysis more valuable. Before making a pricing, lending, settlement, or improvement decision, obtain the facts that reflect how the market sees the home now.