Clearwater, Tampa, St. Petersburg, Cape Coral, and Fort Myers property owners often ask whether a desktop appraisal vs full appraisal will give them the value they need. The answer depends less on convenience and more on the purpose of the assignment, the property’s characteristics, and the level of support a lender, court, attorney, or other intended user requires. A credible appraisal begins with a clearly defined scope of work, not a one-size-fits-all report.
Desktop Appraisal vs Full Appraisal: What Changes?
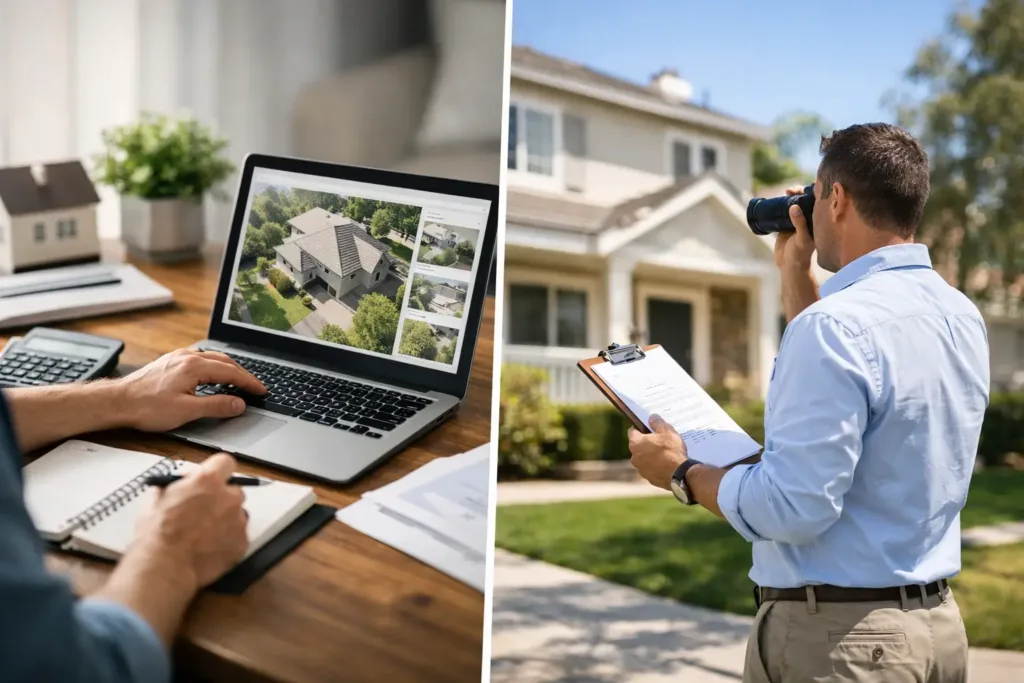
The central difference is the inspection. In a desktop appraisal, the appraiser typically develops an opinion of value without personally inspecting the property. The analysis may rely on public records, multiple listing service data, prior appraisal information, photographs, floor plans, aerial imagery, tax records, market data, and information supplied by the client or another reliable source.
A full appraisal generally includes a physical inspection by the appraiser. For a typical residential assignment, that means observing the exterior and interior, measuring or verifying the home’s physical characteristics as appropriate, noting condition and features, and comparing the property to recent competitive sales. The appraiser then prepares a report that explains the analysis and value conclusion.
Neither label automatically tells you whether an appraisal is good or bad. A desktop assignment may be appropriate when the available property information is reliable and the client’s requirements permit it. A full appraisal is often the stronger choice when interior condition, renovations, functional layout, waterfront influence, damage, or unusual features could materially affect value.
What a Desktop Appraisal Can and Cannot Show
A desktop appraisal can be efficient because it removes the scheduling and travel required for an inspection. In a straightforward refinance or lower-risk lending situation, a lender may determine that a desktop scope is acceptable. It can also be useful when an informed preliminary value opinion is needed and the assignment conditions support analysis without an inspection.
However, the appraiser cannot personally verify what cannot be observed. Public records can be incomplete. Listing photographs may be outdated, selectively presented, or missing altogether. A recent kitchen renovation, concealed deferred maintenance, a converted garage, water intrusion, or a substantially different interior condition may not appear in third-party data.
That limitation matters most in markets where homes that look similar on paper can command very different prices. A Real Estate Appraiser in Tampa may see two homes with the same recorded square footage and bedroom count, yet one has a fully renovated interior while the other requires extensive updates. Without an inspection, the analysis must rely on credible information supplied to the appraiser and clearly state the assignment conditions.
A desktop appraisal should not be confused with an automated valuation model. An AVM is computer-generated. A desktop appraisal is performed by a qualified appraiser who applies market judgment, analyzes comparable sales, and develops a supported opinion within the defined scope of work.
Why a Full Appraisal Carries More Property-Specific Support
A full appraisal gives the appraiser first-hand observations that can affect the final opinion of value. Interior condition is only part of the picture. The appraiser can also identify quality of construction, updating, functional issues, views, site influences, additions, accessory structures, and features that may not be accurately reflected in public records.
For a Home Appraisal in Clearwater, for example, proximity to the water, flood-related market perceptions, condominium condition, view orientation, or a home’s maintenance level may influence buyer behavior. In St. Petersburg, the difference between a carefully restored historic home and a property with significant deferred maintenance can be difficult to capture from data alone. A physical inspection gives the appraiser a more reliable basis for making those distinctions.
A full appraisal is commonly preferred for purchase financing, complex refinancing, estate planning, divorce, litigation, and other matters where the report may receive close review. It is also usually the prudent route for unique homes, luxury properties, older homes, homes with substantial upgrades, and properties where the facts are uncertain.
Which Option Fits Your Situation?
The intended use should drive the decision. If a lender orders the appraisal, the lender sets the assignment requirements. Borrowers and agents generally cannot choose a desktop appraisal simply because it may be faster or less disruptive. The lender must decide whether that scope meets its underwriting and investor guidelines.
For private clients, the question is whether the report needs to withstand scrutiny beyond a casual pricing discussion. A Home Appraiser serving Cape Coral may recommend a full inspection when a property’s canal access, seawall condition, pool features, remodeling, or storm-related repairs are relevant to market value. Similarly, a Real Estate Appraisal in Fort Myers involving an estate, equitable distribution, or attorney review should be based on a scope of work that supports a credible and defensible conclusion.
A desktop appraisal may be reasonable when the property is typical for its neighborhood, the data is current and trustworthy, there are no known condition concerns, and the intended user accepts the assignment conditions. A full appraisal is usually the better fit when a financial, legal, or family decision depends on understanding the property as it actually exists.
The Trade-Off Between Speed and Certainty
Desktop assignments can reduce inspection-related time, but they do not eliminate the need for careful research and analysis. An appraiser still must identify relevant sales, consider market trends, reconcile differences among comparables, and document the basis for the value opinion. Fast work is not a substitute for supported work.
A full appraisal requires access to the property and may take more coordination, particularly for occupied homes, gated communities, condominiums, or properties with tenants. In exchange, it reduces reliance on assumptions about the home’s interior and physical condition. That additional certainty can prevent problems later, especially if the value is challenged or the report is reviewed by a lender, attorney, opposing party, or estate beneficiary.
Cost is also a practical factor. A less extensive scope may cost less in some cases, but the lowest initial fee is not always the lowest-risk decision. If incomplete property information leads to a later dispute, a revised report, or a need for a new inspection-based appraisal, the apparent savings can disappear.
What Makes Either Appraisal Credible?
Credibility comes from more than an inspection choice. The appraiser must be properly qualified for the assignment, independent of the outcome, knowledgeable about the local market, and compliant with applicable appraisal standards. The scope of work must be sufficient to produce credible results for the intended use.
The report should clearly identify what was and was not inspected, the sources of information used, the relevant market data, and the reasoning behind adjustments and the final value conclusion. If a desktop appraisal depends on client-provided photos, renovation details, or property descriptions, those assumptions and limiting conditions should be disclosed rather than hidden.
For homeowners, lenders, attorneys, and agents, clarity is a meaningful trust signal. A well-supported report explains the value. It does not simply provide a number.
When the stakes involve financing, probate, divorce, settlement, or a major sale decision, choose the scope that matches the risk. My Florida Home Appraisal can help clients determine whether an inspection-based residential appraisal is appropriate for their specific property and intended use.