Clearwater, Tampa, St. Petersburg, Cape Coral, and Fort Myers homeowners often ask the same question once a loan, sale, estate, or legal deadline is in motion: how long does a home appraisal take? The property visit itself may take less than an hour, but a credible appraisal is not complete when the appraiser leaves the driveway. A well-supported opinion of value requires local market research, comparable-sale analysis, reconciliation, and a USPAP-compliant report.
For many standard single-family homes, the full process takes about five to 10 business days from assignment to completed report. Timing can be faster when access is easy and recent comparable sales are plentiful. It can take longer for waterfront property, unique homes, complex assignments, or periods when appraiser demand is high.
How Long Does a Home Appraisal Take From Start to Finish?
A residential Real Estate Appraisal generally has three stages: scheduling, the on-site inspection, and report development. Each stage affects the delivery date.
Once an assignment is received, the appraiser must coordinate access with the homeowner, agent, tenant, or property contact. In an active purchase transaction, that often means working around inspection periods, contractor visits, and occupancy schedules. A vacant home may be easier to access, but lockbox approval or agent coordination can still be required.
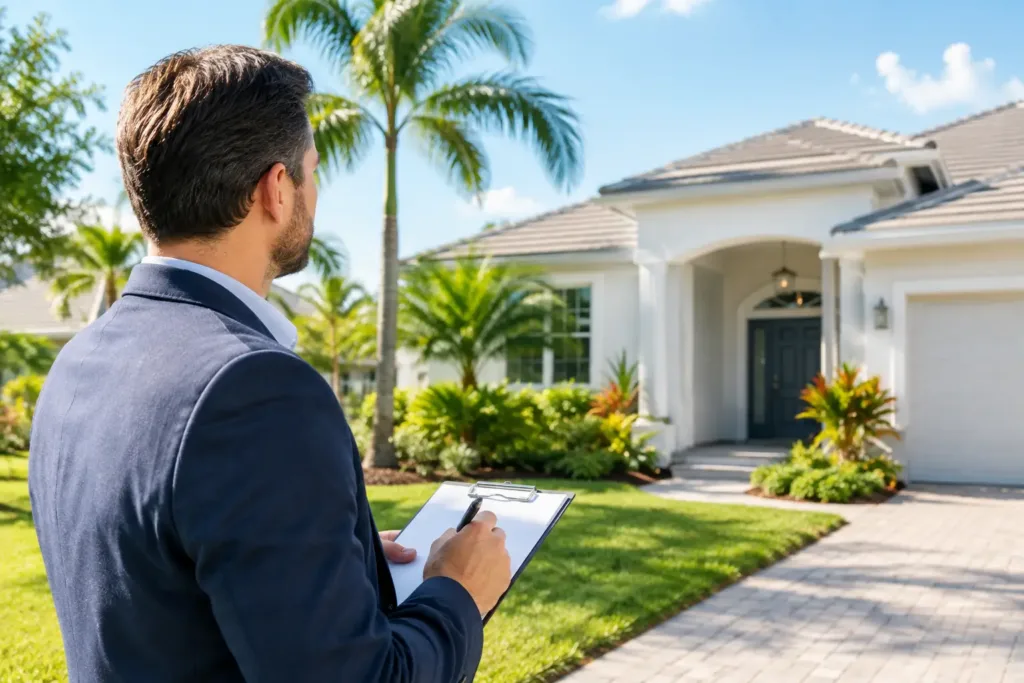
The inspection comes next. For a typical home, a Home Appraiser may spend 30 minutes to two hours at the property. The time depends on square footage, condition, improvements, site characteristics, and the complexity of the home. The appraiser observes and documents features that affect value, such as gross living area, bedroom and bathroom count, quality, condition, remodeling, pools, views, garages, and obvious deferred maintenance.
Afterward, the largest portion of the assignment begins. The appraiser researches the neighborhood, verifies public and MLS data, selects and analyzes comparable sales, considers market conditions, and writes the appraisal report. This work is why an accurate valuation should not be judged by the length of the site visit alone.
The Inspection Is Usually the Shortest Part
A common misunderstanding is that a Home Appraisal is finished when the property inspection ends. The inspection is essential, but it is only one component of the valuation process.
A Real Estate Appraiser must determine which recent sales are truly comparable to the subject property. That requires more than finding homes nearby with a similar number of bedrooms. Location within a market area, water influence, lot size, age, design, effective age, updates, condition, school boundaries, and buyer preferences can all matter. A condominium, for example, may require review of the specific building, unit location, amenities, HOA information, and recent sales within the same development.
In Clearwater, Tampa, St. Petersburg, Cape Coral, and Fort Myers, neighborhood boundaries can change value quickly. A home near the water, in a historic district, on a canal, or within a gated community may need more detailed analysis than a similar-looking home only a few blocks away. The report must explain the support for the final value opinion, not simply produce a number.
What Can Make an Appraisal Take Longer?
Most delays are understandable and can be avoided with early planning. The following situations commonly extend the appraisal timeline:
- Limited property access. Missed appointments, tenant coordination, pets that cannot be secured, or inaccessible areas can require a return visit.
- Complex or unusual properties. Waterfront homes, acreage, luxury residences, historic properties, new construction, and homes with extensive additions may require deeper research.
- Few comparable sales. In neighborhoods with low turnover or highly varied housing, finding recent, relevant sales takes more time.
- Incomplete information. Missing permits, unclear renovation details, incorrect public records, or uncertainty about finished living area can require additional verification.
- Lender or assignment requirements. Mortgage lending appraisals may involve specific forms, additional documentation, review processes, or revision requests.
- High market volume. During active purchase and refinance periods, scheduling availability can be more limited.
A faster report is useful, but speed should never replace adequate analysis. An appraisal that is rushed, poorly supported, or based on weak comparable sales can create problems for a lender, buyer, seller, attorney, or court later in the process.
Purchase, Refinance, Estate, and Legal Appraisals Have Different Timelines
The reason for the appraisal matters. A mortgage lender typically orders the appraisal through its own process, and the borrower may not be able to select the appraiser directly. The appraisal report may be completed promptly, but lender review and underwriting can add time before the borrower receives a final loan decision.
For a private pre-listing or pre-purchase appraisal, the client can often arrange the assignment directly with the appraiser. This can provide more flexibility on scheduling and communication. Sellers may use an independent valuation to price a home with stronger market support, while buyers may seek clarity before making a major financial commitment.
Estate, probate, divorce, and litigation assignments may take longer because the effective date of value may be in the past rather than the current date. A retrospective appraisal requires research into market conditions and sales available as of that historical date. Court-related matters may also require especially clear reporting and documentation because the appraisal could be reviewed by attorneys, opposing parties, or a judge.
How to Help Your Home Appraisal Stay on Schedule
Property owners cannot control every part of the process, but they can reduce avoidable delays. Confirm access early and make sure the appraiser can reach all rooms, the garage, outbuildings, and relevant exterior areas. If there is a gate code, lockbox, alarm, or tenant, provide clear instructions before the appointment.
It also helps to prepare a concise record of significant improvements. Include the year completed, approximate cost when available, and whether permits were obtained. A new roof, HVAC replacement, impact windows, kitchen renovation, bathroom remodel, pool work, solar installation, or major addition may affect marketability and value. Receipts are not required for every update, and cost does not automatically equal added value, but accurate information helps the appraiser understand the property.
Keep the home safe and accessible. Normal lived-in condition is not a problem, and a house does not need to look like a staged listing. However, blocked access to rooms, severe clutter that prevents observation, or areas that cannot be inspected may lead to questions or a follow-up visit.
If you are involved in a purchase or refinance, ask the lender early about the appraisal order date and anticipated turnaround. A buyer should not wait until the last days of the financing contingency to learn that the appraisal has not yet been scheduled. Agents and lenders can help by confirming contact information, providing contract details when appropriate, and responding quickly if the appraiser has a factual question.
Why Local Experience Can Affect Both Speed and Quality
An experienced local appraiser starts with familiarity that cannot be replicated by an automated valuation model. Understanding which subdivision boundaries matter, how buyers respond to a particular school zone, or why a canal, flood exposure, view, or condominium building affects value can make the research more efficient and more credible.
That does not mean every local appraisal should be rushed. It means the analysis begins with a stronger foundation. A state-certified appraiser who knows the market can identify relevant comparable sales, recognize when a sale needs further verification, and explain market-based adjustments with greater clarity.
For private clients, My Florida Home Appraisal provides residential valuation services supported by local market knowledge, more than 25 years of hands-on experience, and USPAP-compliant reporting. The goal is not merely a quick number. It is an unbiased, defensible value opinion that clients can use with confidence.
When Should You Follow Up?
If the appraiser has completed the inspection, allow time for the research and report-writing stage before assuming something is wrong. For a standard assignment, a polite status request after the agreed turnaround date is reasonable. If a deadline is firm, communicate it when ordering the appraisal rather than after the inspection.
For lender-ordered work, remember that the appraiser may be required to communicate through the lender or appraisal management process. The lender is usually the right contact for report status, underwriting questions, and delivery expectations.
A home appraisal timeline is best viewed as a balance of access, property complexity, market data, and reporting requirements. Planning early and working with a qualified local professional gives the process its best chance of moving promptly without sacrificing the accuracy your financial decision deserves.