Clearwater, Tampa, St. Petersburg, Cape Coral, and Fort Myers buyers and sellers can face the same uncomfortable moment just before closing: the lender’s appraisal comes in below the agreed purchase price. The contract may be signed, inspections may be complete, and moving plans may already be underway. Knowing how to handle appraisal gap issues at that point can protect your financing, your earnest money, and your ability to make a sound decision.
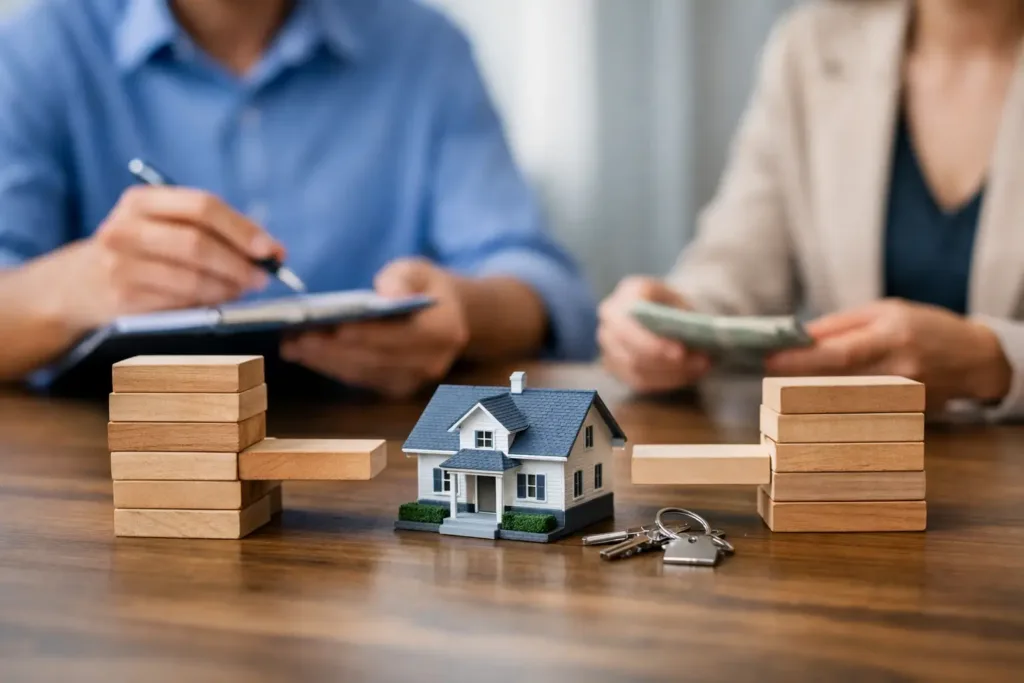
An appraisal gap is not automatically a sign that someone acted improperly or that the transaction must fail. It means the property’s appraised value is lower than the contract price, creating a difference that the lender usually will not finance. The right response depends on the contract terms, the buyer’s available funds, the strength of the appraisal support, and whether the parties can reach a revised agreement.
What an appraisal gap means for your loan
Lenders base their loan amount on the lower of the purchase price or appraised value. For example, assume a buyer agrees to pay $500,000 with 20 percent down, but the Home Appraisal supports a value of $475,000. The lender will generally calculate the loan against $475,000, not $500,000.
That does not necessarily mean the buyer only needs to bring the $25,000 difference. If the buyer wants to preserve the original loan-to-value ratio, the required cash can be more substantial because the down payment is applied to the appraised value. The buyer should ask the lender for a revised loan estimate before making any decision. Assumptions made at the kitchen table often differ from the lender’s actual figures.
The first document to review is the purchase contract. An appraisal contingency may give the buyer the right to renegotiate or cancel within a defined period if the value is low. A buyer who waived that protection, or agreed to an appraisal-gap provision, may have fewer options and more financial exposure. Deadlines matter. Missing a contingency deadline can weaken a party’s negotiating position or affect earnest money rights.
How to handle an appraisal gap without rushing
A low appraisal calls for a measured review, not an immediate argument over value. The appraiser’s role is to provide an independent opinion based on market evidence, property characteristics, and the intended use of the report. Appraisers cannot simply adjust a conclusion to match a contract price, and lenders must preserve appraiser independence.
Start by obtaining and reading the appraisal report carefully. Confirm the property address, legal description, living area, bedroom and bathroom count, lot size, condition observations, and improvements. A factual error can affect the analysis. Also look at the comparable sales used, their sale dates, locations, condition, and adjustments.
A contract price may exceed the appraised value for understandable reasons. Perhaps multiple buyers competed for a home with a waterfront setting, a renovated interior, a rare floor plan, or a location near a desired school or employment center. Those factors may be valid, but they still need market support. A buyer’s willingness to pay more than recent comparable sales does not, by itself, establish market value for lending purposes.
Consider a reconsideration of value when evidence supports it
If the report contains material errors or overlooks stronger comparable sales, the buyer’s lender may allow a reconsideration of value request. This process is typically submitted through the lender, not directly to the appraiser. A real estate agent can help organize relevant evidence, such as recent closed sales that were available on the appraisal effective date and are genuinely comparable.
The most effective request is specific and fact-based. It identifies an error, explains why a suggested comparable is superior or more similar, and provides verified data. A long list of active listings, pending sales, or homes from a different market segment is usually less persuasive. The goal is not to pressure the appraiser. It is to ensure the appraisal considered accurate, relevant information.
A reconsideration may result in no change. That outcome does not necessarily reflect a flawed report. It can mean the additional information does not alter the market-supported conclusion. Buyers and sellers should plan for that possibility rather than treating a review request as a guaranteed solution.
The main ways buyers and sellers resolve the difference
Once the loan implications and appraisal evidence are clear, the parties generally have several paths forward. The best choice depends on the amount of the gap and each party’s priorities.
The buyer can bring additional cash to closing and proceed at the original price. This can make sense for a buyer who intends to own the property long term, has adequate reserves after closing, and believes the home’s unique features justify the premium. The trade-off is immediate: the buyer may begin ownership with less equity than anticipated.
The seller can reduce the purchase price to the appraised value. This is often the cleanest route when the buyer has financing constraints and the seller wants certainty of closing. It may also be practical when returning the property to the market could lead to another appraisal issue or a longer marketing period.
The parties can split the gap through a negotiated price reduction. For example, a seller may lower the price by part of the difference while the buyer contributes additional cash for the remainder. This approach can preserve the transaction while sharing the financial impact.
A buyer may also change financing, increase the down payment, or use a different loan structure if the lender permits it. These options should be discussed directly with the loan officer because qualification standards, mortgage insurance, interest rates, and closing timelines can change.
Finally, if the contract allows it and an agreement cannot be reached, the buyer may terminate under the appraisal contingency. This is not a failure. It can be the financially responsible decision when paying above supported value would compromise the buyer’s goals or reserves.
Why local market evidence matters
Real Estate Appraisal work is highly local. A comparable sale several miles away may be meaningful in one neighborhood and unsuitable in another. In Clearwater, Tampa, St. Petersburg, Cape Coral, and Fort Myers, value can change materially based on water access, flood considerations, neighborhood boundaries, age and condition, condominium restrictions, view influences, and renovation quality.
That is why buyers and sellers should be cautious about relying on automated estimates or broad market headlines when a transaction is at stake. A qualified Real Estate Appraiser in Clearwater, Tampa, St. Petersburg, Cape Coral, and Fort Myers analyzes the specific property and the relevant competitive market. A local Home Appraiser considers the features buyers in that immediate area actually recognize and pay for.
For private decisions outside a lender transaction, an independent Home Appraisal in Clearwater, Tampa, St. Petersburg, Cape Coral, and Fort Myers can also be useful before listing, making an offer, settling an estate, dividing assets, or preparing for litigation. The intended use and scope of work should be clear from the beginning, particularly when the report may need to withstand review by attorneys, lenders, or courts.
Avoid the mistakes that make a gap harder to solve
Do not assume a new lender will automatically produce a higher value. A second appraisal can differ, but it also can reach the same or a lower conclusion, while adding cost and delay. Do not ask an appraiser to “hit” a number. Ethical appraisal practice and USPAP standards require independence and impartiality.
Sellers should avoid dismissing the appraisal without examining the market evidence. If a buyer exits and the home returns to the market, future buyers and agents may ask why the prior contract did not close. Buyers, meanwhile, should avoid draining every available reserve to cover a gap without considering repairs, insurance, relocation expenses, and the realities of early homeownership.
Clear communication is often the difference between a resolved appraisal gap and a lost transaction. The lender should explain the financing impact, the agent should provide reliable market context, and the buyer and seller should focus on their actual options rather than on a number they hoped to see.
A well-supported valuation does more than determine a loan amount. It gives everyone at the closing table a credible basis for deciding whether the agreed price, the financing, and the risk still make sense.