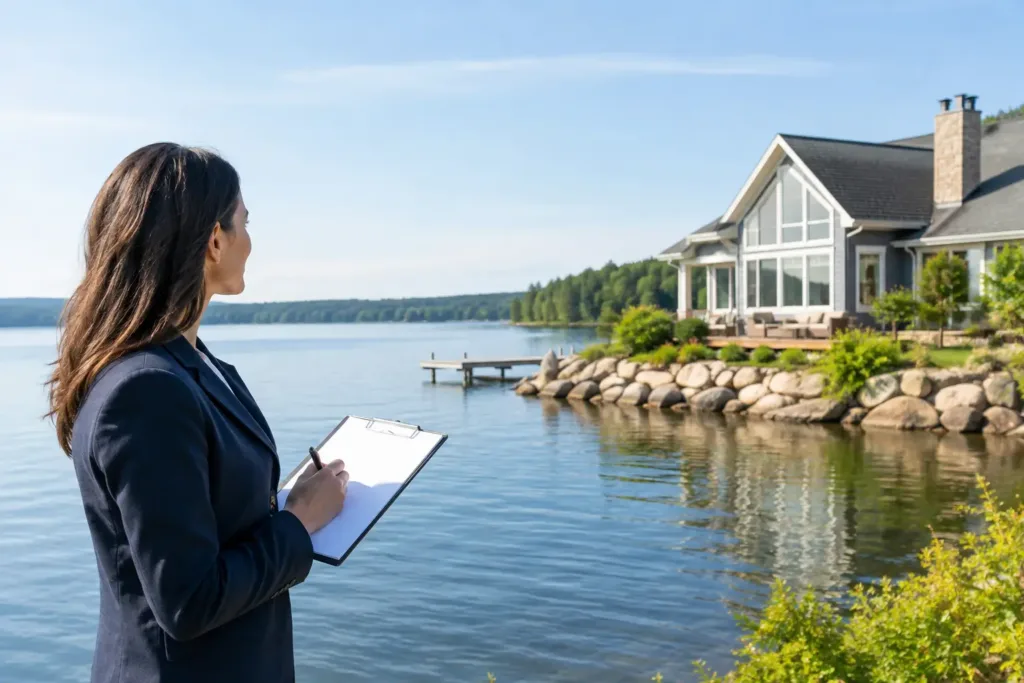
Clearwater, Tampa, St. Petersburg, Cape Coral, and Fort Myers waterfront homes can look similar from the street yet command materially different values. This waterfront property appraisal guide explains why a dock, canal view, beach access, seawall condition, or location on open water can change the analysis – and why the highest nearby sale is not automatically the best comparable.
For homeowners, buyers, lenders, attorneys, and agents, waterfront valuation requires more than a standard square-foot comparison. A credible appraisal must separate the value of the residence from the value, utility, condition, and risk associated with the water location. The result should be an unbiased opinion that is well supported, clearly explained, and appropriate for its intended use.
Why Waterfront Homes Require a Different Valuation Approach
Waterfront property is not one market. A home on a protected canal may appeal to boat owners because of its route to open water, while a gulf-front condominium may command value for views, beach proximity, and rental demand. A lakefront setting may offer privacy and scenery but no boating access. Each can be desirable, but they are not interchangeable.
A Real Estate Appraiser evaluates the specific property rights and physical characteristics conveyed with the home. That includes the type of water frontage, view corridor, access, improvements, and any limitations that affect typical buyer behavior. Two homes with the same living area, age, and finish level may have different market values because one has direct access to navigable water and the other does not.
The appraisal is also a point-in-time opinion of market value. It reflects what informed buyers and sellers were doing as of the effective date, not what an owner hopes the waterfront lifestyle should be worth. This distinction is particularly important when a property has unique features or when sales activity is limited.
The Waterfront Features an Appraiser Examines
Water Type, View, and Access
The first question is simple: what does the buyer actually receive? A broad bay view, gulf frontage, a river setting, a saltwater canal, a freshwater canal, or lake frontage can attract different buyer pools and produce different sale patterns.
Access matters as much as appearance. For boating-oriented properties, an appraiser may consider distance to open water, bridge clearance, canal width and depth, tidal conditions, and whether the route is practical for the type of boat a typical buyer may own. A scenic canal with restricted access may not compete directly with a property offering quick, unobstructed access to open water.
Views also require careful comparison. A full, protected water view is different from a partial view between neighboring homes. The market may recognize a premium for sunsets, unobstructed sight lines, beach frontage, or a corner location with water on two sides, but the evidence must come from relevant sales rather than assumptions.
Docks, Lifts, Seawalls, and Other Site Improvements
Waterfront improvements can contribute meaningful value, but their contribution is not always equal to their installation cost. A newer dock, working boat lift, appropriate pilings, and well-maintained seawall may improve utility and marketability. Conversely, a deteriorated seawall, unpermitted structure, or dock in need of replacement can create a buyer concern and affect value.
An appraiser observes the apparent condition and utility of these items but does not perform an engineering inspection. If visible conditions raise a concern, the appraisal may disclose the issue and, when appropriate, rely on a qualified inspection or repair estimate. This protects the client from treating a visible condition problem as a minor cosmetic detail.
Flood Exposure, Insurance, and Regulatory Factors
Waterfront ownership can involve flood-zone considerations, insurance costs, elevation requirements, coastal construction standards, and local permitting rules. These factors do not automatically reduce value. In many markets, buyers accept them as part of owning a highly desirable water-oriented property.
Still, a change in insurance availability, a known history of flooding, or a significant cost to maintain a seawall can influence buyer demand. The proper appraisal question is not whether a risk exists in the abstract. It is whether the market recognizes that risk through sales prices, marketing times, concessions, or buyer preferences.
Comparable Sales Are the Foundation of a Defensible Appraisal
The strongest waterfront appraisal begins with sales that buyers would reasonably consider alternatives. Proximity helps, but it is not enough. A nearby inland sale may help measure the value of the house itself, yet it may offer little support for the waterfront component.
A Home Appraiser analyzes recent closed sales, active listings, pending transactions when relevant, and market trends. The goal is to identify properties with similar waterfront influence, location appeal, physical utility, quality, condition, and date of sale. Adjustments are then considered for meaningful differences, such as direct versus indirect access, dock utility, view quality, lot size, living area, renovations, and pool features.
There are times when no comparable is perfect. This is common for custom homes, rare beachfront locations, and properties with unusual dockage or water access. In those cases, a competent appraiser expands the search thoughtfully while explaining why each selected sale is relevant. A report should never hide the fact that a property is distinctive; it should address the distinction directly.
What Homeowners Can Provide Before the Inspection
A homeowner does not need to prove a value to the appraiser. However, accurate property information can improve the completeness of the report and prevent important features from being overlooked.
Before the inspection, gather permits and invoices for major renovations, dock or seawall work, roof replacement, impact windows, pool improvements, and other substantial updates. If the property has a boat lift, provide basic information on its capacity and installation date if available. A recent survey, elevation certificate, homeowner association documents, and details about water access can also be useful.
It is also reasonable to provide a short list of sales you believe are relevant. The appraiser will independently determine whether those transactions are comparable, but local knowledge from an owner or agent can help identify a feature that is not obvious in public records. Keep the discussion factual. Documents and property details are more useful than a target value.
Appraisal Purpose Changes the Scope of the Assignment
A mortgage appraisal must meet lender and secondary-market requirements in addition to USPAP standards. A private appraisal may be needed for a pre-listing decision, estate settlement, divorce, tax appeal, trust planning, or litigation support. The intended use affects the report format, research depth, effective date, and level of explanation required.
For example, a retrospective estate valuation may require the appraiser to analyze what the market supported on a date in the past. A current-date listing consultation focuses on present market conditions. A litigation assignment may require more detailed documentation and a report designed to withstand scrutiny from attorneys, opposing experts, or a court.
When ordering the appraisal, state the intended use clearly. A Real Estate Appraisal in Clearwater, Tampa, or St. Petersburg should be assigned with the same care as a Home Appraisal in Cape Coral or Fort Myers: the report must fit the decision it is meant to support.
Common Waterfront Appraisal Misunderstandings
One common misconception is that every dollar spent on waterfront improvements returns dollar for dollar in market value. Buyers may value a new seawall or dock because it reduces immediate maintenance concerns, but the market may not pay the full project cost as a separate premium.
Another is that tax assessments establish market value. Assessments serve a government purpose and may reflect a different valuation date, methodology, or assessment limitation. They can be informative background, but they are not a substitute for an independent appraisal.
Finally, automated estimates are especially limited with waterfront homes. Public data may not capture the quality of the view, bridge restrictions, usable dockage, seawall condition, or the difference between a quiet basin and direct open-water access. A Home Appraiser in Tampa or a Real Estate Appraiser in Fort Myers who understands the local waterfront market can analyze those distinctions with far more precision than a broad algorithm.
Choose Experience That Matches the Property
Waterfront valuation is not a place for shortcuts. Look for a state-certified appraiser with experience in the immediate market, a clear understanding of USPAP requirements, and the ability to explain the comparable-sales analysis in plain language. A reliable report identifies both favorable and unfavorable factors rather than advocating for a desired result.
My Florida Home Appraisal provides independent residential valuation services built on local market knowledge, careful research, and clear reporting. For a waterfront decision involving financing, a sale, an estate, or a legal matter, the right next step is to request an appraisal that identifies what buyers are truly paying for the water – and what they are not.