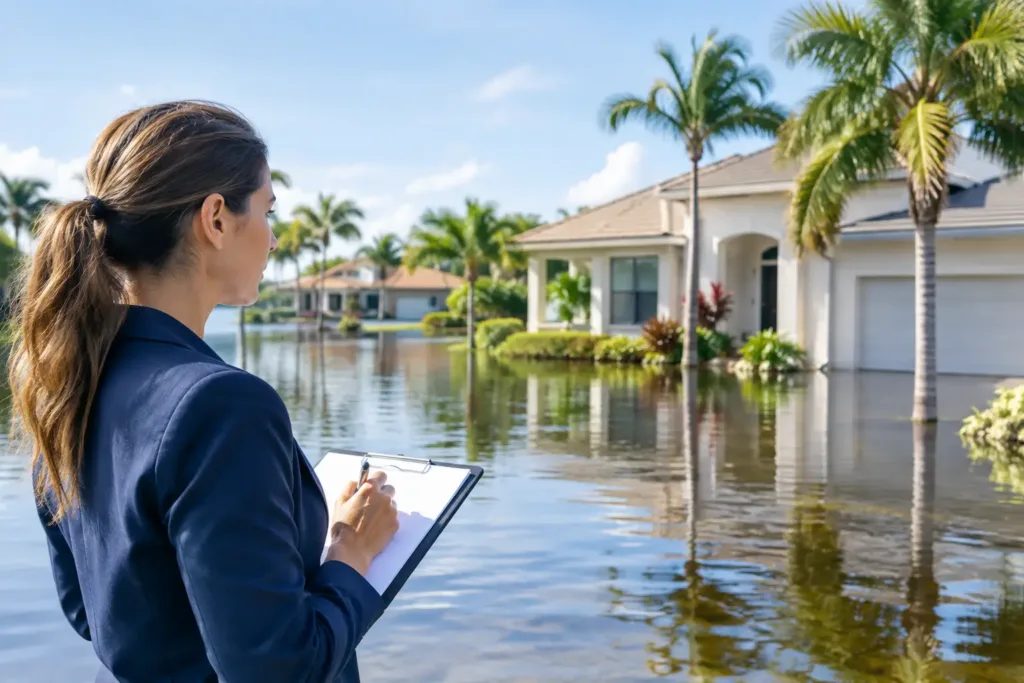
Clearwater, Tampa, St. Petersburg, Cape Coral, and Fort Myers homeowners often ask the same difficult question after a storm or a flood disclosure: what does flood exposure do to a home’s value? This Fort Myers flood valuation guide explains how a qualified appraiser analyzes that question with market evidence rather than assumptions.
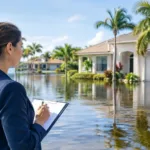
A property’s flood history, flood zone, insurance requirements, elevation, repairs, and buyer perception can all affect value. But there is no automatic percentage adjustment that applies to every home. Two nearby properties can react very differently to the same flood event depending on the extent of damage, the quality of repairs, the cost of insurance, and what buyers are currently willing to pay.
Why Flood Valuation Requires More Than an Online Estimate
Automated estimates can be useful as a broad starting point, but they do not reliably identify whether a specific home has experienced water intrusion, whether remediation was properly completed, or whether its flood risk differs from nearby sales. Those details matter in Fort Myers, where coastal conditions, canals, storm surge exposure, drainage patterns, and insurance costs can vary substantially within a relatively small area.
A Real Estate Appraisal considers the property itself and the market’s reaction to it. The appraiser develops an opinion of market value using recent, relevant sales and applies supportable adjustments when there are meaningful differences. A lender, attorney, estate representative, or homeowner needs that analysis to be objective, documented, and compliant with USPAP, the standards that govern professional appraisal practice.
Flood-related valuation is especially fact-specific. A home located in a designated flood zone is not necessarily worth less than a comparable home outside that zone. Conversely, a home outside a mapped high-risk zone may still have a known history of water intrusion that buyers consider relevant. The question is not simply whether flood risk exists. The question is how informed buyers and sellers respond to that risk in the current market.
Fort Myers Flood Valuation Guide: The Factors That Matter
Flood zone, elevation, and insurance obligations
Flood zone designations and elevation information help establish risk and potential carrying costs. If a buyer must obtain flood insurance as a condition of financing, the premium can influence affordability and demand. The effect may be modest for one property and more substantial for another, particularly when insurance costs are significantly higher than competing homes.
An elevation certificate, when available, can provide helpful context regarding the structure’s elevation relative to applicable flood levels. It is not an appraisal document, but it may help explain insurance requirements and support a more informed analysis. An appraiser does not determine insurance eligibility or quote premiums, yet reliable insurance information can be relevant to marketability.
Documented flood damage and the quality of repairs
Past water intrusion does not always produce the same market response. A property that sustained limited damage, was promptly remediated, and has clear repair records may compete differently than a property with unresolved moisture issues, visible defects, or incomplete documentation.
Receipts, permits, contractor invoices, photographs, mitigation reports, and proof of completed repairs can be useful. These records do not automatically restore value dollar for dollar, but they give buyers, lenders, and appraisers evidence of the property’s condition. If damage remains or conditions are uncertain, a Real Estate Appraiser may need to report those observations and, where appropriate, make the appraisal subject to repair, inspection, or additional information.
Comparable sales after the event
Comparable sales are central to credible flood valuation. The most persuasive evidence usually comes from homes that sold after the market had time to react to the relevant event or risk disclosure. Ideally, the sales have similar locations, design, age, condition, utility, flood exposure, and buyer profile.
This is where timing matters. Sales that occurred before a major storm may not reflect current buyer attitudes, reconstruction costs, or insurance conditions. On the other hand, relying only on distressed sales immediately after a storm can also produce a misleading result if those transactions involved unusual pressure, incomplete repairs, or cash-only circumstances.
A competent analysis weighs the full market context. It may include post-event repaired sales, unaffected competing sales, active listings, pending contracts, and broader neighborhood trends. The goal is not to select the lowest sale. It is to determine which evidence best reflects the actions of typical buyers and sellers.
Buyer perception and marketability
Market value is influenced by what a typical informed buyer would pay. Flood concerns can affect that decision through anticipated insurance costs, fear of future loss, financing limitations, repair uncertainty, or the simple preference for a different location. Yet buyer perception may be tempered by strong waterfront demand, a desirable neighborhood, updated construction features, or demonstrated resilience after prior storms.
That is why a flood adjustment cannot be borrowed from another city or applied as a standard rule. A well-supported appraisal explains the evidence rather than relying on a generalized penalty.
What Homeowners Should Gather Before a Home Appraisal
A Home Appraiser cannot advocate for a target value, but accurate property information helps prevent avoidable uncertainty. Before the inspection, homeowners should prepare records that clarify the home’s history and current condition.
Useful documentation may include the date and nature of any water intrusion, invoices for demolition and repairs, permits and final inspections, remediation or mold reports, insurance claim records when appropriate, elevation documentation, and information about current flood insurance. If the home has been renovated after damage, a concise list of improvements with dates and costs is also helpful.
Be direct about known prior damage. A clear explanation with documentation is generally more useful than an unclear history that raises questions later in underwriting, negotiations, or litigation. The appraiser’s role is to provide an unbiased opinion, not to punish a homeowner for a past event or to overlook relevant facts.
When You Need an Independent Appraisal
For a typical purchase loan or refinance, the lender usually orders the appraisal. In other situations, an independent appraisal may be the appropriate choice. Homeowners and professionals often seek a private appraisal when setting a listing strategy, negotiating a post-storm sale, resolving an estate, dividing assets in divorce, reviewing a prior appraisal, or supporting a legal matter.
The intended use affects the scope of work. An estate or litigation assignment may require a retrospective value opinion as of a specific date, while a current listing consultation focuses on present market conditions. A lender appraisal must also meet lender and secondary-market requirements. Discussing the purpose at the outset helps ensure the assignment is developed for the right decision.
For property owners seeking a Home Appraisal Fort Myers residents can rely on, independence matters. The report should identify relevant flood-related influences, explain the comparable-sale selection, and distinguish observed conditions from unsupported conclusions.
Local Knowledge Supports Better Comparable Selection
Local market knowledge is particularly valuable when flood exposure differs from one neighborhood to the next. A Real Estate Appraiser Fort Myers homeowners hire should understand how canal-front, riverfront, coastal, inland, and newer elevated construction can compete differently. The same principle applies across the firm’s service areas: a Home Appraiser Clearwater clients use may analyze coastal and inland comparables differently, while a Real Estate Appraisal Tampa assignment may require careful attention to neighborhood-level drainage, insurance, and buyer demand.
Likewise, a Home Appraisal St. Petersburg report, Real Estate Appraiser Cape Coral assignment, or Home Appraisal Cape Coral review should not treat a map label as the entire story. Property-specific features and actual market evidence remain the foundation of a credible conclusion.
My Florida Home Appraisal provides state-certified residential appraisal services built on local market knowledge, objective analysis, and USPAP-compliant reporting. For flood-affected or flood-exposed homes, experience with complex property histories can make a meaningful difference in how clearly the valuation is supported.
A Defensible Value Starts With Evidence
Flood exposure may influence value, but it does not define a property’s value by itself. The strongest valuation considers the home’s condition, documented repairs, insurance implications, elevation, location, and the behavior of buyers in the current market. When the stakes involve financing, sale pricing, an estate, or a dispute, clear evidence and an unbiased appraisal provide a far better foundation than a generic estimate.