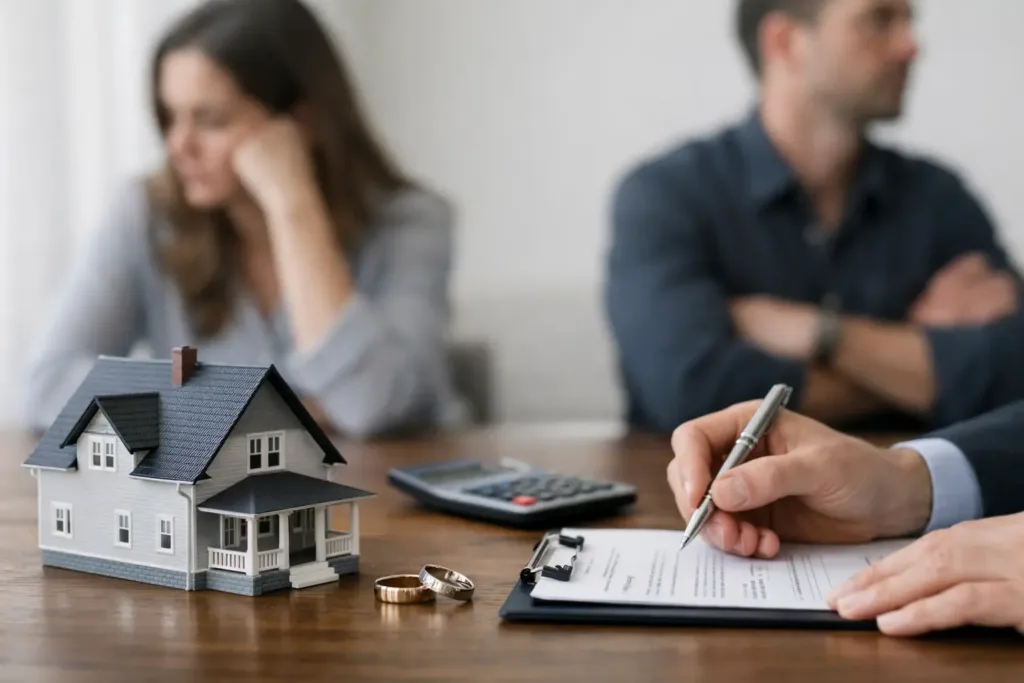
In Clearwater, Tampa, St. Petersburg, Cape Coral, and Fort Myers, a home can be one of the largest assets addressed in a divorce. Understanding how divorce appraisal works helps both parties move beyond opinions, online estimates, and listing-price assumptions toward an unbiased opinion of market value that can support settlement discussions or court proceedings.
A divorce appraisal is not about deciding who should keep the property. It is a professional Real Estate Appraisal that establishes what the home was worth on a specified date, using recognized appraisal methods, local market evidence, and a clearly supported report. That value may affect a buyout amount, the division of sale proceeds, refinancing decisions, and the overall equitable distribution of marital assets.
Why a Divorce Appraisal Is Different From a Sale Estimate
A real estate agent’s comparative market analysis can be useful when preparing to list a home. It is designed to help set a competitive asking price, often with an eye toward current buyer behavior and marketing strategy. A divorce appraisal has a different purpose: it provides an independent, credible value opinion from a state-certified Real Estate Appraiser.
The appraiser has no financial interest in whether the home sells, who retains it, or what settlement either party prefers. That independence matters when property value becomes a point of disagreement. A well-supported appraisal report explains the data considered, the comparable sales selected, the adjustments made, and the reasoning behind the final value conclusion.
Online valuation tools have an even more limited role. They can be a starting point for casual research, but they may not account for recent renovations, deferred maintenance, waterfront influence, condominium rules, a changing neighborhood, or the specific condition of the property. Those details can materially affect value in markets such as Tampa Bay and Southwest Florida.
The First Question: What Is the Effective Date of Value?
Before the inspection is scheduled, the parties, their attorneys, or the court should identify the required effective date of the appraisal. This is the date the value opinion applies to. It may be the current date, the date of separation, the date a petition was filed, or another date established by agreement or court direction.
This distinction can be significant. If the local market changed substantially between separation and settlement, a current-value appraisal could differ from a retrospective appraisal, which estimates what the property was worth at an earlier point in time. The report must clearly state its effective date and use market data appropriate to that date.
A retrospective appraisal is not simply an old online estimate. The Home Appraiser researches sales, listings, and market conditions that were known or reasonably available as of the historical valuation date. That work requires careful analysis, particularly when the requested date is years in the past.
How the Divorce Home Appraisal Process Usually Works
1. The assignment is defined clearly
The appraiser confirms the property address, intended use, intended users, ownership information, effective date, and scope of work. In a divorce matter, it is helpful to establish early whether one party is ordering the appraisal privately, both parties are jointly retaining the appraiser, or an attorney or court is involved.
The appraisal engagement should also address access to the property and communication expectations. When possible, a jointly commissioned appraisal can reduce duplicated costs and avoid competing value opinions. That said, each situation depends on the parties’ level of agreement and the guidance of their legal counsel.
2. The property is inspected
The Home Appraiser visits the residence to observe its physical characteristics and condition. This generally includes the home’s size, room count, layout, construction quality, updates, visible maintenance concerns, site features, and amenities. The appraiser also considers factors such as a pool, garage configuration, views, waterfront access, rental features, or condominium location within a development.
An appraisal inspection is not a home inspection. The appraiser is not testing systems or providing a repair list. However, visible condition issues can affect marketability and value. Homeowners should provide practical documentation when available, including renovation details, permits, HOA information, surveys, floor plans, and records of major improvements.
Both spouses do not need to be present for the inspection unless the engagement requires it. The key issue is that the appraiser receives reasonable access and accurate property information without pressure to reach a particular number.
3. The appraiser analyzes the market
After the inspection, the appraiser researches comparable sales. These are recently sold properties that buyers viewed as reasonable alternatives to the subject home. The best comparables are not always the closest properties geographically. They must also be similar in location, design, size, condition, features, and sale timing.
The appraiser then analyzes differences between each comparable sale and the subject property. For example, a renovated home may require an adjustment when compared with a similar home in original condition. A waterfront property, a premium lot, a pool, or a superior school-area location can also require analysis. The goal is not to average sale prices. It is to determine what the subject property would likely have sold for under the market conditions applicable to the effective date.
For a Home Appraisal Clearwater property, market boundaries can shift quickly between neighborhoods, flood zones, and waterfront versus non-waterfront locations. The same is true for a Home Appraisal Tampa residence where urban location, historic character, and redevelopment activity can influence buyer demand. Local knowledge is not an add-on to the process. It is central to selecting and interpreting relevant market data.
4. A written report is prepared
The completed report presents the appraiser’s conclusion and the support behind it. Depending on the assignment, it may include a property description, neighborhood analysis, photographs, a sales comparison grid, maps, market-condition discussion, and explanations of adjustments or unusual factors.
A credible divorce appraisal should be prepared in compliance with the Uniform Standards of Professional Appraisal Practice, commonly called USPAP. Compliance helps ensure the report follows recognized standards for independence, disclosure, analysis, and reporting. It does not guarantee that both parties will like the value, but it gives the conclusion a defensible professional foundation.
How the Value Is Used in a Divorce Settlement
Once the value is established, the parties and their attorneys can determine how it fits into the broader financial picture. If one spouse intends to keep the home, the appraisal may be used to calculate a buyout after considering mortgage balances, liens, closing costs where applicable, and the division terms negotiated or ordered.
If the home will be sold, the appraisal can help set realistic expectations for pricing and projected net proceeds. It can also identify whether a proposed listing price is out of step with supported market value. In some cases, a refinance is needed so the spouse keeping the property can remove the other spouse from the mortgage. The lender may require its own appraisal for the loan, even if a divorce appraisal has already been completed.
That is not necessarily a contradiction. A lender appraisal and a divorce appraisal can have different clients, intended uses, effective dates, and underwriting requirements. If the reports differ, compare the assignment conditions and market evidence before assuming one is incorrect.
What Happens When Spouses Disagree With the Appraisal?
Disagreement is common when a home carries financial and personal significance. The appropriate response is to review the report carefully, not to rely on a preferred online estimate or a neighbor’s sale price. Look for factual issues first: incorrect living area, omitted improvements, an inaccurate condition description, or a comparable sale that clearly differs from the property in a material way.
If there is credible new information, the client may request that the appraiser consider it. An appraiser can correct factual errors or address relevant data, but cannot simply revise a conclusion because one party wants a higher or lower result. When the dispute remains significant, each side may obtain an independent appraisal, or the matter may require appraisal review or litigation support.
A Home Appraisal St. Petersburg assignment, for example, may require close attention to neighborhood boundaries, historic-home features, proximity to water, and condition differences that are not visible in broad automated data. For a Home Appraisal Cape Coral or Home Appraisal Fort Myers property, canal access, seawall condition, waterfront orientation, hurricane-related repairs, and changing inventory can also require careful local analysis.
Choosing an Appraiser for a Divorce Matter
The appraiser’s qualifications and relevant experience matter because the report may be reviewed by attorneys, mediators, opposing counsel, lenders, or a court. Look for a state-certified professional with demonstrated knowledge of the immediate market, experience with private and legal-use assignments, and a commitment to USPAP-compliant reporting.
Communication also matters. A reliable appraiser should explain the scope of work, requested documents, expected turnaround time, and what the report can and cannot do. The appraiser provides an independent value opinion, not legal advice or a recommendation about how assets should be divided.
For homeowners needing a Home Appraisal Tampa, Home Appraisal Clearwater, Home Appraisal St. Petersburg, Home Appraisal Cape Coral, or Home Appraisal Fort Myers, the most useful report is one that is accurate, well documented, and tailored to the assignment rather than generated from a formula.
Divorce already requires difficult decisions. Obtaining a credible, locally supported appraisal gives those decisions a clearer financial foundation and allows both parties to focus on workable next steps.